Specialist Finance for Semi-Commercial Property
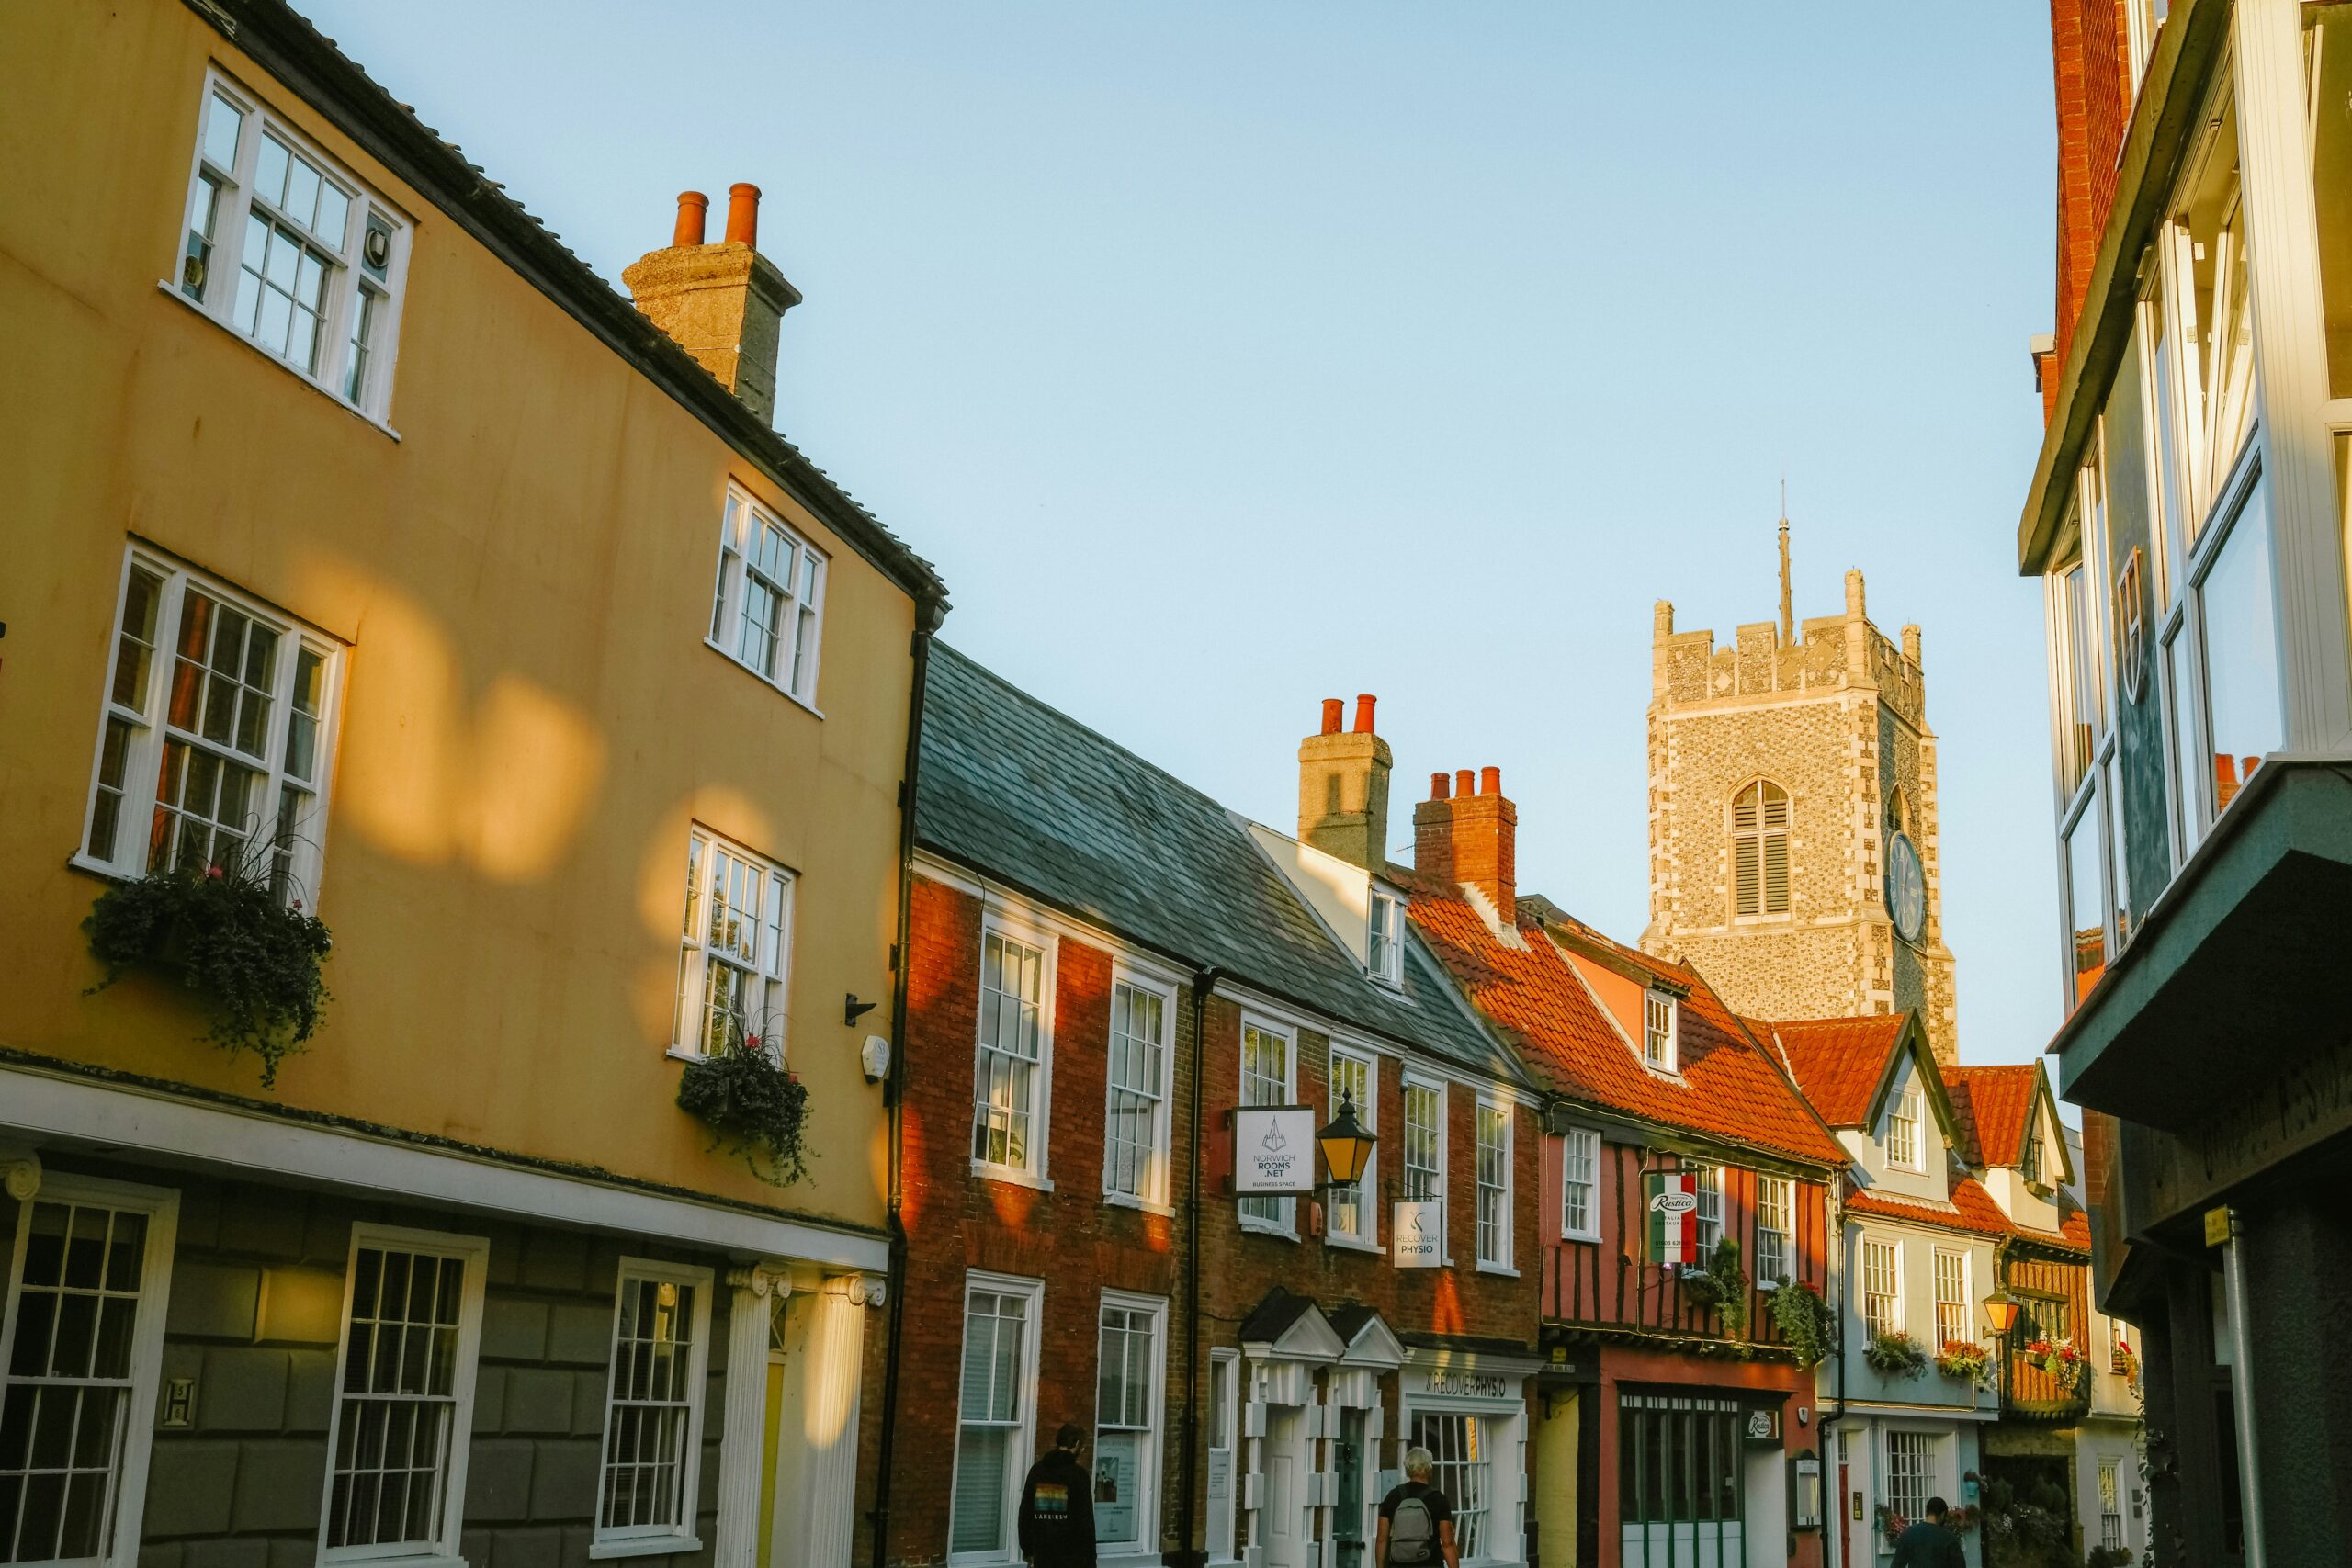
Semi-commercial property — buildings that combine residential and commercial use, such as a flat above a shop — sits in a niche corner of the property market that many mainstream lenders are reluctant to touch. Brightstar Financial, an FCA-regulated specialist finance broker based in Billericay, Essex, works with a panel of lenders who understand these complexities and may be able to help property investors and business owners explore suitable funding options.
What Makes Semi-Commercial Property Finance Different
Because semi-commercial properties blend two distinct uses under one roof, lenders assess them differently from standard residential or purely commercial assets. The income streams, tenancy arrangements, and valuation methods all carry added complexity. As a result, standard high-street mortgage products are often unsuitable, and borrowers may need to look at specialist commercial mortgage solutions or bridging finance to meet their needs. The right product will depend on individual circumstances, the nature of the property, and how it is being used or developed.
How Brightstar Financial Can Help
Brightstar Financial operates as a specialist finance broker, meaning they work across a wide range of lending products rather than being tied to a single lender. This includes commercial mortgages, bridging finance, development finance, and buy-to-let mortgages, among others. For semi-commercial properties, their brokers can assess a borrower’s situation and search their lender panel to identify options that may be appropriate. As an FCA-regulated firm, Brightstar Financial is required to act in accordance with the Financial Conduct Authority’s rules around fair treatment of customers and clear financial promotions.
Frequently Asked Questions
Can I get a mortgage on a semi-commercial property? It is possible, though not straightforward. Lenders who do offer finance on these properties often apply commercial underwriting criteria, which means the application process and requirements can differ significantly from a residential mortgage. Speaking with a specialist broker may help clarify what options could be available depending on your circumstances.
What types of semi-commercial properties are typically considered? Properties commonly considered in this category include shops, offices, or other commercial units with residential accommodation above or attached. Each property is assessed individually, and lender appetite can vary depending on factors such as location, condition, tenancy, and the proportion of commercial to residential space.
Is bridging finance an option for semi-commercial purchases? Bridging finance is sometimes used for semi-commercial acquisitions, particularly where speed is important or where a longer-term mortgage is not immediately available. However, bridging loans are short-term products secured against property, and it is important to understand the risks and exit strategy before proceeding. Your property may be at risk if you do not keep up repayments on any loan secured against it.
If you are looking at a semi-commercial property and want to understand what finance options might be available to you, Brightstar Financial welcomes enquiries. Their team can talk through your situation and explain what routes may be worth exploring, without any obligation to proceed.